CRE PROPTECH NEWS
CoStar Closed on Zonda. The Number That Matters Isn’t $800M.
CoStar Group completed its $800 million all-cash acquisition of Zonda on August 21 and furnished the press release to the SEC the same day on a Form 8-K. Zonda brings a lot-level new home construction database, homebuilder software, more than 3,000 customers, and the NewHomeSource.com and Livabl marketplaces. In 2025 it generated approximately $170 million of revenue at a 23 percent Adjusted EBITDA margin, the company says.
Direct answer
Direct answer to CoStar Zonda acquisition
The purchase price is not the operator’s number. The operator’s number is how many datasets in their own stack now answer to one vendor. CoStar already owned CoStar, LoopNet, Apartments.com, Homes.com, STR, Ten-X and Matterport. Adding Zonda means land and construction data can sit beside comps, rents, hospitality benchmarks and spatial capture under one parent, one renewal posture, and one set of license terms governing what an AI system may read.
What CoStar filed on August 21
CoStar Group, Inc. (NASDAQ: CSGP) filed a Form 8-K on August 21, 2026 reporting that it had completed its acquisition of Bora, Inc. and its subsidiaries, together Zonda, for $800 million in cash. The filing is signed by Chief Financial Officer Robin Rossmann and lists the company’s principal executive offices at 1201 Wilson Blvd, Arlington, Virginia. One structural detail is worth naming because it changes what a reader is entitled to assume: the disclosure came under Item 7.01, Regulation FD, rather than under Item 2.01, completion of acquisition of assets, and the company states expressly that the information in Item 7.01 and in Exhibit 99.1 is “furnished” and not “filed” for purposes of Section 18 of the Securities Exchange Act. No pro forma financial statements accompany it. The 8-K carries the press release and nothing more, which means the numbers below are company disclosures rather than audited or reconciled statements.
The press release furnished as Exhibit 99.1 sets out the substance. CoStar announced the agreement to acquire Zonda on May 29, 2026, and says the transaction has now satisfied the required regulatory approvals and customary closing conditions. Zonda is described as a provider of new home construction data, homebuilder software and residential real estate marketplaces, serving more than 3,000 customers including large homebuilders, developers, suppliers and lenders. In 2025 it generated approximately $170 million of revenue at an Adjusted EBITDA margin of 23 percent, per the release. At its core, CoStar says, is a proprietary lot-level database covering new home communities, land development activity, construction status, home sales and builder operations, used by customers for underwriting, land strategy, capital allocation, development planning, forecasting and sales operations. The acquisition also brings the NewHomeSource.com and Livabl consumer marketplaces. Andy Florance, Founder and Chief Executive Officer, is quoted calling new residential construction “a massive market” whose information and digital marketplace opportunities “remain significantly underdeveloped,” and Jeff Meyers, President of Zonda, is quoted on gaining scale and resources. CoStar sizes the United States new home market at approximately $400 billion in annual home sales and states that this is greater than the United States multifamily rental market. BofA Securities served as financial advisor and Latham & Watkins LLP as legal advisor. For context the release supplies its own second-quarter figures: $925 million in revenue, up 18 percent year over year, Adjusted EBITDA more than doubling to $184 million, and residential revenue up 33 percent to $444 million.
Why a CRE operator should care
Read this as a data-supply story rather than a price story, because that is where it touches an operator. Before August 21, a firm underwriting land or build-to-rent could plausibly hold a Zonda subscription for lot-level construction and community data and a separate CoStar subscription for commercial comps, and those were two vendors, two renewal calendars, and two negotiations. They are now one parent. Set that beside what CoStar already owned and the shape becomes clearer: CoStar for commercial data and analytics, LoopNet for commercial listings, Apartments.com for apartment rentals, Homes.com for residential, STR for hospitality benchmarking, Ten-X for auction, Matterport for spatial capture, and Domain and OnTheMarket abroad. Land and new construction data was one of the remaining categories a CRE firm bought somewhere else. To be precise about what is and is not being claimed here: nothing in the 8-K or the press release says anything about pricing, bundling, or contract terms for the combined data, and PSV is not predicting a price increase. What changed is structural. A renewal conversation that used to be split across two counterparties can now be one counterparty’s conversation, and that is true whether or not anyone ever exercises it.
The AI-specific consequence is the one PSV keeps returning to, and it is not about model capability. It is about license terms. Whether a dataset can enter an AI workflow at all is decided by the subscription agreement, not by the software: what the agreement says about machine reading, bulk export, derived works, and redistribution determines what a firm may legally build on top of it, and PSV has covered CoStar’s own terms and enforcement record separately. The practical effect of consolidation is that the terms question consolidates with it. A firm that wanted to put land, comps, and rent data into one grounded workflow used to be reading three agreements from three companies with three risk postures. More of that reading now resolves to a single vendor’s standard form and a single vendor’s appetite for how its data is used by machines. That cuts both directions and it would be dishonest to present it only as a downside: one counterparty can also mean one negotiation, one clarified permission, and one answer instead of three. What it does not mean is that a firm can skip the reading. The agreements a firm signed before August 21 still govern until they are replaced.
The workflow PSV would run
The first workflow is a data-license and renewal inventory, and it is a records exercise rather than a strategy exercise. The inputs are documents a firm already has: every executed subscription agreement and order form, the seat counts, the renewal date, the termination notice window, the auto-renewal language, and the clauses covering export, machine reading, derived works and redistribution. Add one field a firm usually does not track, which is the current parent company of each vendor. An assistant reads each agreement against a fixed question set and returns one cited row per dataset: who owns this vendor today, what the agreement permits and prohibits regarding machine reading and derived works, when it renews, how many days of notice a non-renewal requires, and which internal decisions stop working if the dataset goes away. Every cell cites the section of the agreement it came from, and anything the agreement is silent on is marked unverified rather than inferred. The reviewer is whoever signs the renewals, working with counsel. The approval gate is firm: counsel confirms each license reading against the executed agreement before any dataset is wired into an AI workflow. A license summary produced by a model is a draft for a lawyer to check, never an opinion, and treating it as one is how a firm ends up in breach with a well-formatted table explaining why it thought otherwise.
The second workflow is a substitution map, and it exists to answer the question a renewal conversation actually turns on. For each dataset, name the decisions it feeds, then name the fallback record if it were unavailable or repriced: the public record, the county source, the direct broker relationship, the internal deal history, or nothing at all. The output is a one-page dependency map with the honest entries left honest, because “there is no substitute” is a real and useful finding when it is true. An assistant assembles and maintains the map; the judgment about what is genuinely substitutable belongs to the people who use the data. The point of doing this now, while nothing has changed commercially, is that it is a calm exercise today and a rushed one during a renewal. PSV is not suggesting a firm drop any vendor. The recommendation is narrower: know your dependency before someone else has a reason to price it.
What stays human, and what the record does not settle
The operator read
Finish with the judgment call.
The reported facts are above. Enter your email for PSV's operator conclusion and a year of access to every newsroom brief.
Free. No card. Privacy policy. Unsubscribe anytime.
 by PSVLive
Build the workflow behind this analysis. Train with the operators doing it.
Real deal files, live builds, and production-ready CRE AI workflows inside the CRE AI Institute.


Clear answers
Common questions about CoStar Zonda acquisition
How much did CoStar pay for Zonda?
$800 million in cash. CoStar Group, Inc. reported the completed acquisition of Bora, Inc. and its subsidiaries, together Zonda, on a Form 8-K filed with the SEC on August 21, 2026, signed by Chief Financial Officer Robin Rossmann. CoStar announced the agreement on May 29, 2026, and the press release furnished as Exhibit 99.1 states the transaction has satisfied the required regulatory approvals and customary closing conditions. Two details are worth noting for anyone relying on the filing. The disclosure came under Item 7.01, Regulation FD, rather than Item 2.01, and CoStar states expressly that the information is furnished and not filed for purposes of Section 18 of the Securities Exchange Act. No pro forma financial statements accompany it, so the operating figures in the release are company disclosures rather than audited or reconciled statements.
What does Zonda actually own that CoStar wanted?
A proprietary lot-level database and the customer relationships around it. Per CoStar, the database covers new home communities, land development activity, construction status, home sales and builder operations, and customers use it for underwriting, land strategy, capital allocation, development planning, forecasting and sales operations. Zonda serves more than 3,000 customers including large homebuilders, developers, suppliers and lenders, and generated approximately $170 million of revenue in 2025 at a 23 percent Adjusted EBITDA margin, according to the company. The deal also brings the NewHomeSource.com and Livabl consumer marketplaces, which focus exclusively on new construction and carry builder-contributed listings with floor plans, pricing, incentives and virtual tours. CoStar sizes the United States new home market at approximately $400 billion in annual home sales, a company characterization for which the release supplies no source.
What does the CoStar Zonda deal mean for a CRE firm's data stack?
It removes a vendor boundary rather than changing a price. A firm underwriting land or build-to-rent could previously hold Zonda for lot-level construction data and CoStar for commercial comps, which meant two counterparties, two renewal calendars and two negotiations. Those are now one parent, alongside LoopNet, Apartments.com, Homes.com, STR, Ten-X and Matterport. Nothing in the filed record addresses pricing, bundling or license terms for the combined data, so no conclusion about cost is available from it. The AI-relevant consequence is that license terms decide whether a dataset may enter an AI workflow at all, since the subscription agreement governs machine reading, bulk export, derived works and redistribution. More of that reading now resolves to one vendor's standard form. The agreements signed before August 21 still govern until they are replaced, so the practical step is a license and renewal inventory reviewed by counsel.
Primary source record
These records support the reported facts in this brief. PSV’s CRE workflow interpretation and test plan are original analysis.
- CoStar Group, Inc., Form 8-K, Item 7.01 and Item 9.01, filed with the SEC August 21, 2026
- CoStar Group, Inc., Exhibit 99.1, “CoStar Group Completes Acquisition of Zonda, Expanding into New Home Data, Analytics and Online Marketplaces,” press release dated August 21, 2026
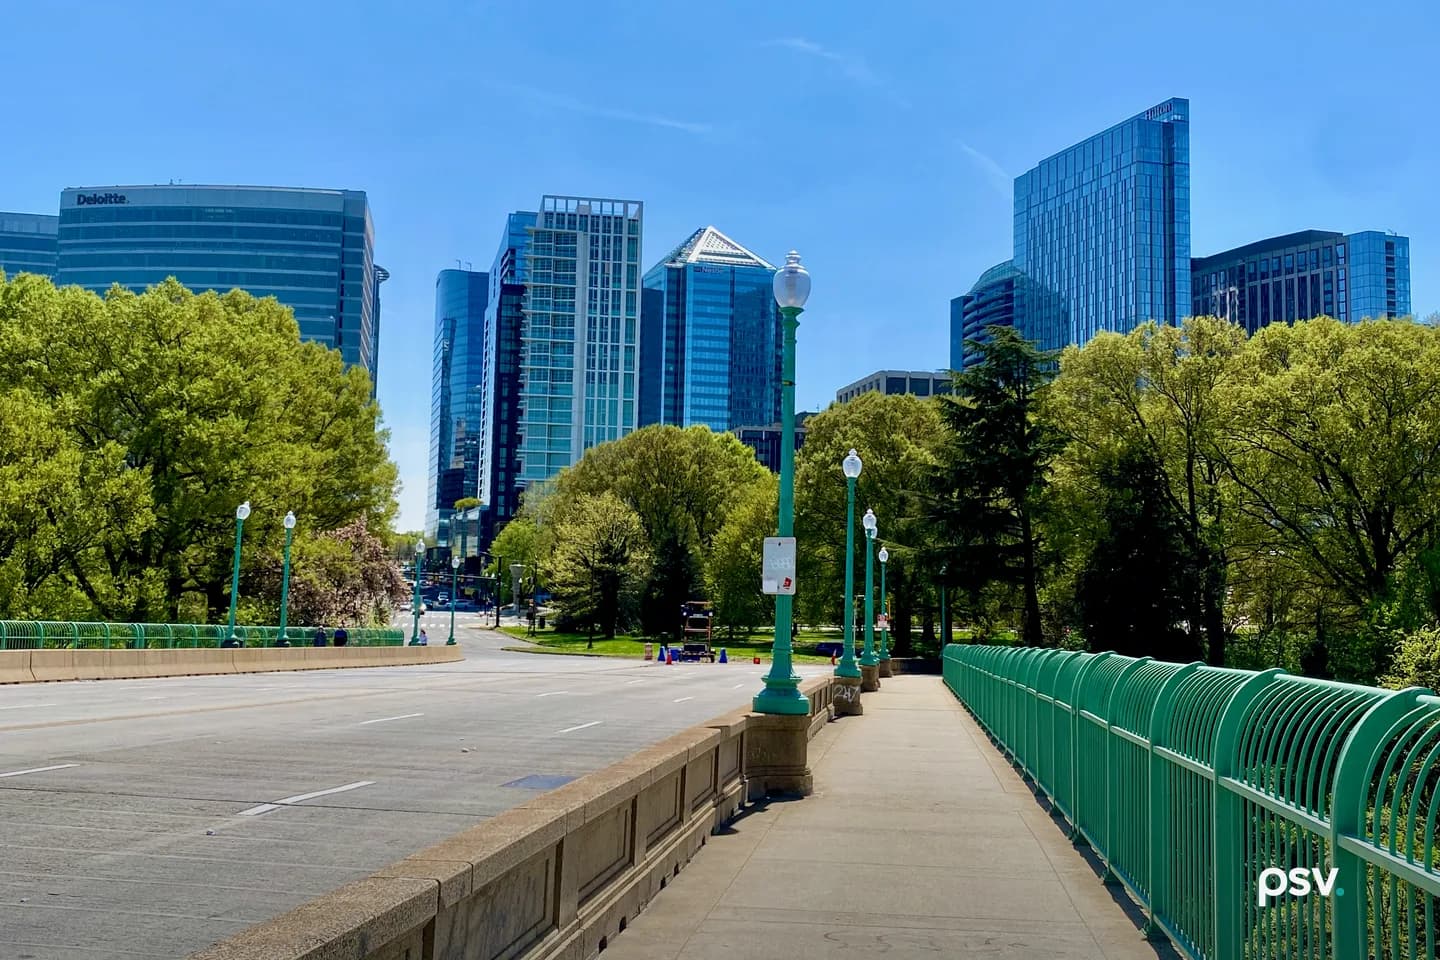
- Wikimedia Commons, “Rosslyn Skyline 2026” by Wikipedian1234, CC BY 4.0 (source of the lead photograph)
Topics
Related PSV analysis
AI TOOL SELECTION
Can You Put a CoStar Export Into Claude or ChatGPT? Read the July 2026 Clause First
Can you upload a CoStar export to Claude or ChatGPT, paste comps into a chat, or connect CoStar through an MCP server? CoStar revised its Terms of Use and its License Agreement Terms and Conditions on July 6, 2026, and both now address AI directly. Here is what the clauses say, which version binds your firm, and the AI work that stays clearly allowed.
AI AGENTS
When Your AI Vendor 10x’s the Price, This Is What Saves You
What happens if the vendor goes public and decides to 10x the usage cost? A principal asked PSV that question about an AI stack built on Claude, and it applies equally to ChatGPT, Copilot, and every workflow tool on top of them. It deserves a better answer than reassurance. Prices move, vendors get acquired, models deprecate. The firms that survive repricing without drama share one property, and it is not a clever contract. It is an architecture decision made on day one, and it costs nothing extra to make.
CRE AI ADOPTION
Skip the Yardi API? Run This Test Before Claude Connects
Two operators, same week, same sentence: the API quote was more than the problem is worth. The question behind the Yardi connector news is older and more practical: for a small or mid-size portfolio, does programmatic Yardi access ever pay for itself, or do scheduled report exports cover everything the AI workflows actually need? There is a test that answers it in an afternoon, and most firms have never run it.
Related guides
Cornerstone PSV guides on the workflows in this article.
Best AI Tools for Commercial Real Estate
The pillar guide to choosing CRE AI tools by workflow fit and control, not vendor hype.
Read the guideProptech AI
What proptech AI means, where artificial intelligence actually works in real estate, and what separates useful proptech AI from the hype.
Read the guideClaude Engineering Partner for CRE
What it means to run Claude with an engineering partner: the operating model, the controls, and the handoff.
Read the guideby PSVLiveYou read the operator view. Now learn to run the workflow.
The AI MBA for commercial real estate: the workflows these briefs describe, taught end to end on real deal files, with live builds and a community of CRE operators.