CRE CAPITAL NEWS
Blackstone’s Data Center REIT Buys Into 13 AWS Buildings for $5B
Blackstone Digital Infrastructure Trust, the data center REIT Blackstone listed in May, has signed its first deal: a 75.1% stake in two joint ventures with Amazon that will own 13 newly built data centers in northern Indiana and Mississippi, valued at $5.0 billion and leased back to Amazon. PSV read the two 8-Ks, the contribution agreement and the 10-Q.
Direct answer
Direct answer to Blackstone AWS data center sale-leaseback
BXDC agreed on November 11 to put about $1.9 billion of IPO cash and about $2.5 billion of new mortgage debt into two joint ventures holding 647 megawatts of powered shells. Amazon keeps 24.9% and leases all of it back triple-net for 12 years, extendable to 32, at a 7.0% initial cap rate with 2.75% annual increases. The deal is not closed, depends on its loans, and carries a $150 million termination fee.
What BXDC filed
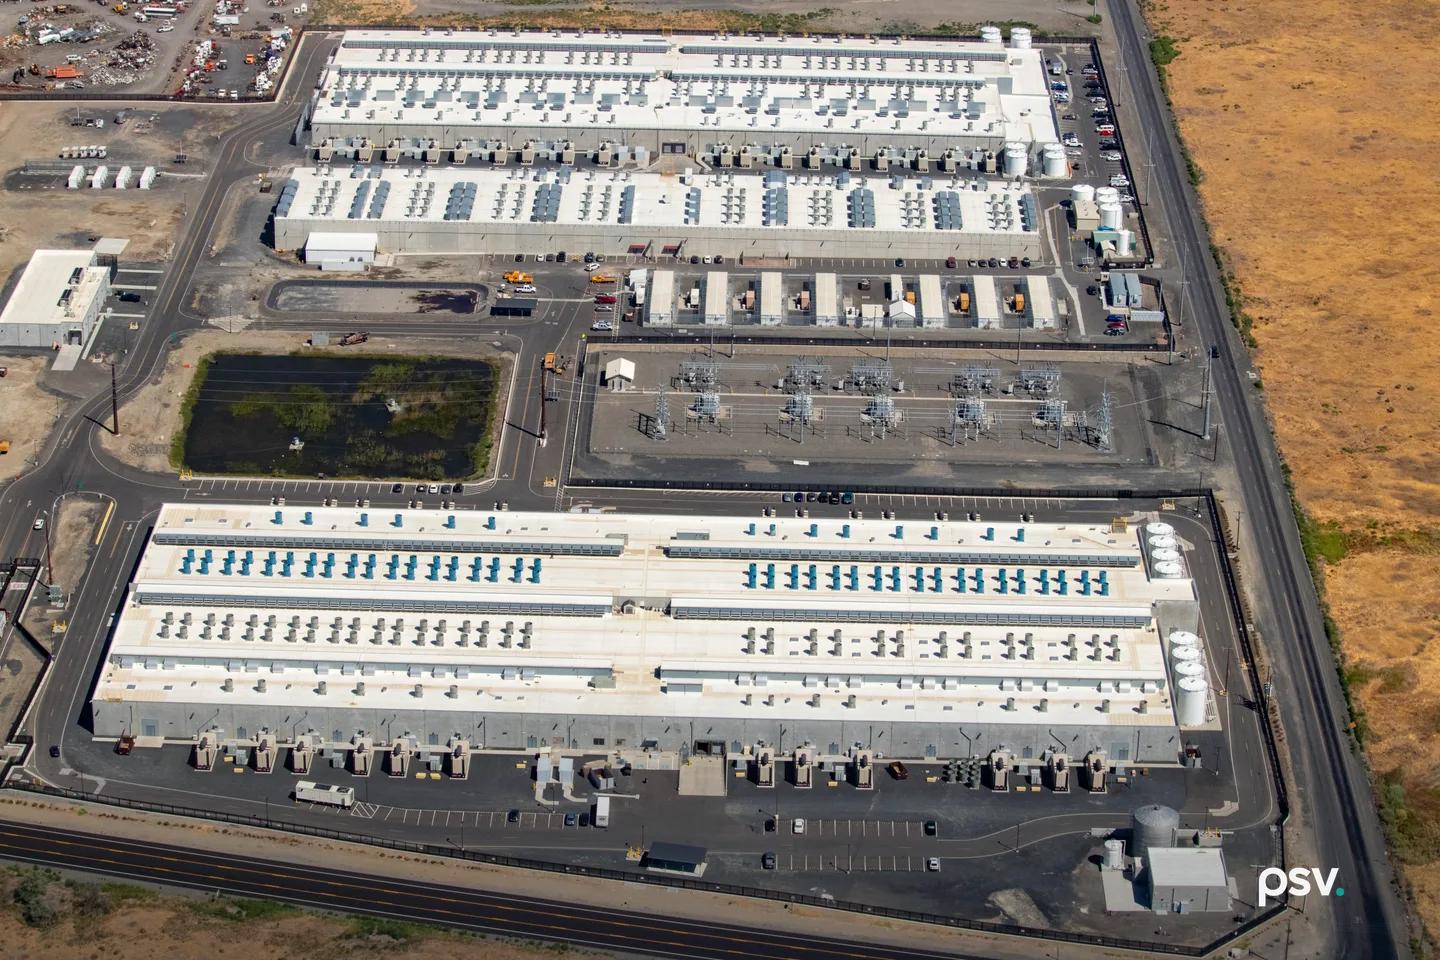
Blackstone Digital Infrastructure Trust (NYSE: BXDC) filed two Form 8-Ks on November 16, 2026. The first, under Item 1.01, says two of its subsidiaries signed a contribution agreement on November 11 with two affiliates of Amazon Data Services, Inc., a subsidiary of Amazon.com, Inc. Under it, BXDC agrees to acquire a 75.1% controlling interest in two limited liability companies that will own two data center campuses: nine buildings in northern Indiana, which the filing places in the greater Chicago market, and four in Mississippi. The 13 buildings are newly constructed and carry 647 megawatts of IT power capacity. The filing values them at $5.0 billion in aggregate, “reflecting an initial capitalization rate of 7.0%.” Amazon contributes the campuses, keeps a 24.9% interest worth $0.6 billion, receives a cash distribution, and leases 100% of both campuses back on triple-net leases guaranteed by Amazon.com, Inc. The leases run a weighted average of 12 years initially, 32 years fully extended, with a 2.75% annual rent increase.
The money comes from two places. BXDC expects to contribute $1.9 billion of the cash it raised in its May IPO, and the rest, including transaction costs, is expected to come from about $2.5 billion of new non-recourse mortgage loans on the properties, for which BXDC says it has debt commitment letters. Either side can walk away if the deal has not closed by December 31, 2026, unless that date is extended, and a party that fails to close owes the other a $150.0 million termination fee as the sole remedy. The second 8-K carries BXDC’s third-quarter results and a transaction presentation. In the press release, CEO Nick Pell calls the deal “a sale-leaseback with Amazon” and says the hyperscaler sale-leaseback channel “doubles our total addressable market.” That is a company claim, not a PSV finding.
Why a CRE operator should care
This is a priced, public comp for a kind of deal that usually trades privately. The presentation defines the 7.0% initial cap rate as first-year base rent divided by aggregate gross value including transaction costs, which computes to about $350 million of first-year rent on the full $5.0 billion, about $263 million of it attributable to BXDC’s 75.1%, on PSV’s arithmetic. The same figures compute to about $7.7 million per megawatt of IT capacity and, as the presentation itself says, about $385 million per building. At 2.75% a year, base rent in year 12 computes to about $472 million. These are powered shells: the filing describes newly constructed data centers leased triple-net to the tenant, and the presentation calls the 7.0% yield “attractive” for “powered shell structure.” A buyer comparing this cap rate to a fully fitted, multi-tenant colocation asset is comparing different products.
The deal also concentrates the REIT. BXDC’s 10-Q says it had neither purchased nor contracted to purchase any investment as of September 30, 2026, when its total assets were about $1.98 billion. Its $1.9 billion contribution is nearly all of that. The Item 1.01 filing names the risk itself: closing would heighten BXDC’s “dependence on one tenant and two properties.” The presentation adds a market argument, citing SemiAnalysis figures that Indiana’s built data center capacity grows from 1,426 megawatts in 2026 to 4,722 in 2028 while Illinois’ goes from 1,605 to 3,071. Those are a third party’s forecasts as quoted by the buyer, not PSV findings. The records also differ on one detail: the press release rounds the stakes to 75% and 25%, while the 8-K, the 10-Q and the presentation’s endnotes say 75.1% and 24.9%.
| Metric | BXDC buy box | Amazon transaction |
|---|---|---|
| Size | $250 million to $1.5 billion or more per building | $5.0 billion for 13 buildings, about $385 million each |
| Markets | Primarily Tier 1 | More than two thirds northern Indiana (greater Chicago), less than one third Mississippi |
| Tenant | Top investment-grade hyperscalers | Amazon affiliate, guaranteed by a parent rated AA by S&P |
| Lease | Primarily triple-net, 10 to 20 years | Triple-net, 12 years initial, 32 years fully extended |
| Rent escalators | 2.0% to 3.0% a year | 2.75% a year |
| Yield | 5.75% to 7.0% or more | 7.0% initial cap rate |
The workflow PSV would run
The artifact is a sale-leaseback comp sheet that a capital markets or acquisitions team keeps for every hyperscale data center trade with a public record. Inputs: the 8-K and its exhibits (here the contribution agreement, with its redactions marked), the form of lease the issuer filed with its registration statement, the transaction presentation, and the issuer’s next 10-Q or 10-K. Output: one line per deal with the gross value and what it includes, the stake acquired, megawatts, building count, first-year rent derived from the stated cap rate, value per megawatt, lease term and renewal structure, escalators, guarantor and rating, debt amount and whether it is funded, closing conditions and outside date, and a column for every place two records disagree. An assistant can extract and compute the line; a person checks each figure against the page it came from.
The reviewer is the head of capital markets or acquisitions. The gate is use: no figure from this deal goes into an underwriting model, an appraisal discussion or a pitch until the reviewer has confirmed it against the filing and marked whether the deal has closed. The sheet is updated when the closing 8-K or the next periodic report lands, because a contribution agreement with committed but unfunded debt is a signed deal, not a completed one.
What stays human, and what the record does not settle
The operator read
Finish with the judgment call.
The reported facts are above. Enter your email for PSV's operator conclusion and a year of access to every newsroom brief.
Free. No card. Privacy policy.
 by PSVLive
Build the workflow behind this analysis. Train with the operators doing it.
Real deal files, live builds, and production-ready CRE AI workflows inside the CRE AI Institute.


Clear answers
Common questions about Blackstone AWS data center sale-leaseback
What did Blackstone Digital Infrastructure Trust buy from Amazon?
BXDC’s November 16, 2026 Form 8-K says it agreed on November 11 to acquire a 75.1% controlling interest in two joint ventures that will own 13 newly constructed data centers with 647 megawatts of IT capacity: nine buildings in northern Indiana and four in Mississippi. Amazon contributes the campuses, keeps 24.9%, and leases all of them back. The deal had not closed as of the filing.
What cap rate did BXDC pay for the AWS data centers?
The filings value the two campuses at $5.0 billion in aggregate, including transaction costs, at a 7.0% initial capitalization rate, defined as first-year base rent divided by that value. On PSV’s arithmetic that is about $350 million of first-year rent, or about $7.7 million of value per megawatt. The leases are triple-net, 12 years initial and 32 fully extended, with 2.75% annual increases.
How is the Blackstone and Amazon data center deal financed?
BXDC expects to contribute $1.9 billion of its IPO proceeds for its 75.1% stake, with Amazon retaining 24.9%, valued at $0.6 billion. The rest, including transaction costs, is expected to come from about $2.5 billion of new non-recourse mortgage loans for which BXDC has commitment letters. Either side can terminate if the deal has not closed by December 31, 2026, with a $150 million termination fee for a failure to close.
Primary source record
These records support the reported facts in this brief. PSV’s CRE workflow interpretation and test plan are original analysis.
- Blackstone Digital Infrastructure Trust, Form 8-K (Items 1.01, 7.01, 9.01) filed November 16, 2026, with Exhibit 2.1 (Contribution Agreement dated November 11, 2026) and Exhibit 99.1 (press release)
- Blackstone Digital Infrastructure Trust, Form 8-K (Items 2.02, 7.01, 9.01) filed November 16, 2026, Exhibit 99.1 (third-quarter 2026 results)
- Blackstone Digital Infrastructure Trust, Transaction Summary, November 2026 (Exhibit 99.2 to the November 16, 2026 Form 8-K)
- Blackstone Digital Infrastructure Trust, Form 10-Q for the quarter ended September 30, 2026 (Note 10, Subsequent Events)
- Lead image: Tedder, “Amazon AWS us-west-2 beach AZ,” Wikimedia Commons, CC BY-SA 4.0
Topics
Track every data center moratorium and large-load rule we have reported, with sources: US data center moratorium tracker.
Related PSV analysis
CRE CAPITAL NEWS
BREIT Books $497M of Impairments as Data Centers Hit 30%
Blackstone Real Estate Income Trust’s third-quarter 10-Q shows $496.7 million of impairment charges, mostly on 13 rental housing properties, against $366.1 million of gains on sales. In the same quarter it put $3.4 billion into pre-leased QTS data center developments, and data centers rose to 30 percent of the portfolio.
CRE AI NEWS
Brookfield’s Q3: Real Estate Raised $900 Million, Then Bought Into Data Centers
Brookfield Asset Management furnished its third quarter results to the SEC on November 6: $25 billion raised in the quarter and $123 billion year to date. Its real estate strategies raised $900 million of that, about 3.6 percent, and the one new real estate commitment it highlighted was a stake in a U.S. hyperscale data center developer.
CRE AI NEWS
Riot Leases All of Corsicana to Anthropic: 910 MW of Powered Land, No Building
Riot Platforms signed a 15-year triple-net powered land lease for its entire 910 critical IT megawatt Corsicana, Texas campus, at $130 per kilowatt a month escalating 3 percent a year. Riot’s release calls the tenant a leading frontier AI lab; its quarterly report on Form 10-Q names Anthropic PBC.
Related guides
Cornerstone PSV guides on the workflows in this article.
Claude for Real Estate Underwriting
The grounded underwriting workflow: real deal documents in, your rules applied, a source citation behind every number, a person signs off.
Read the guideClaude Engineering Partner for CRE
What it means to run Claude with an engineering partner: the operating model, the controls, and who owns what.
Read the guideAI for Real Estate Investing
How commercial real estate investors use AI across the deal lifecycle: sourcing, underwriting, due diligence, and asset management, grounded in real documents.
Read the guideby PSVLiveYou read the operator view. Now learn to run the workflow.
The AI MBA for commercial real estate: the workflows these briefs describe, taught end to end on real deal files, with live builds and a community of CRE operators.